Is an Agentic Bank Run Coming?
Summary
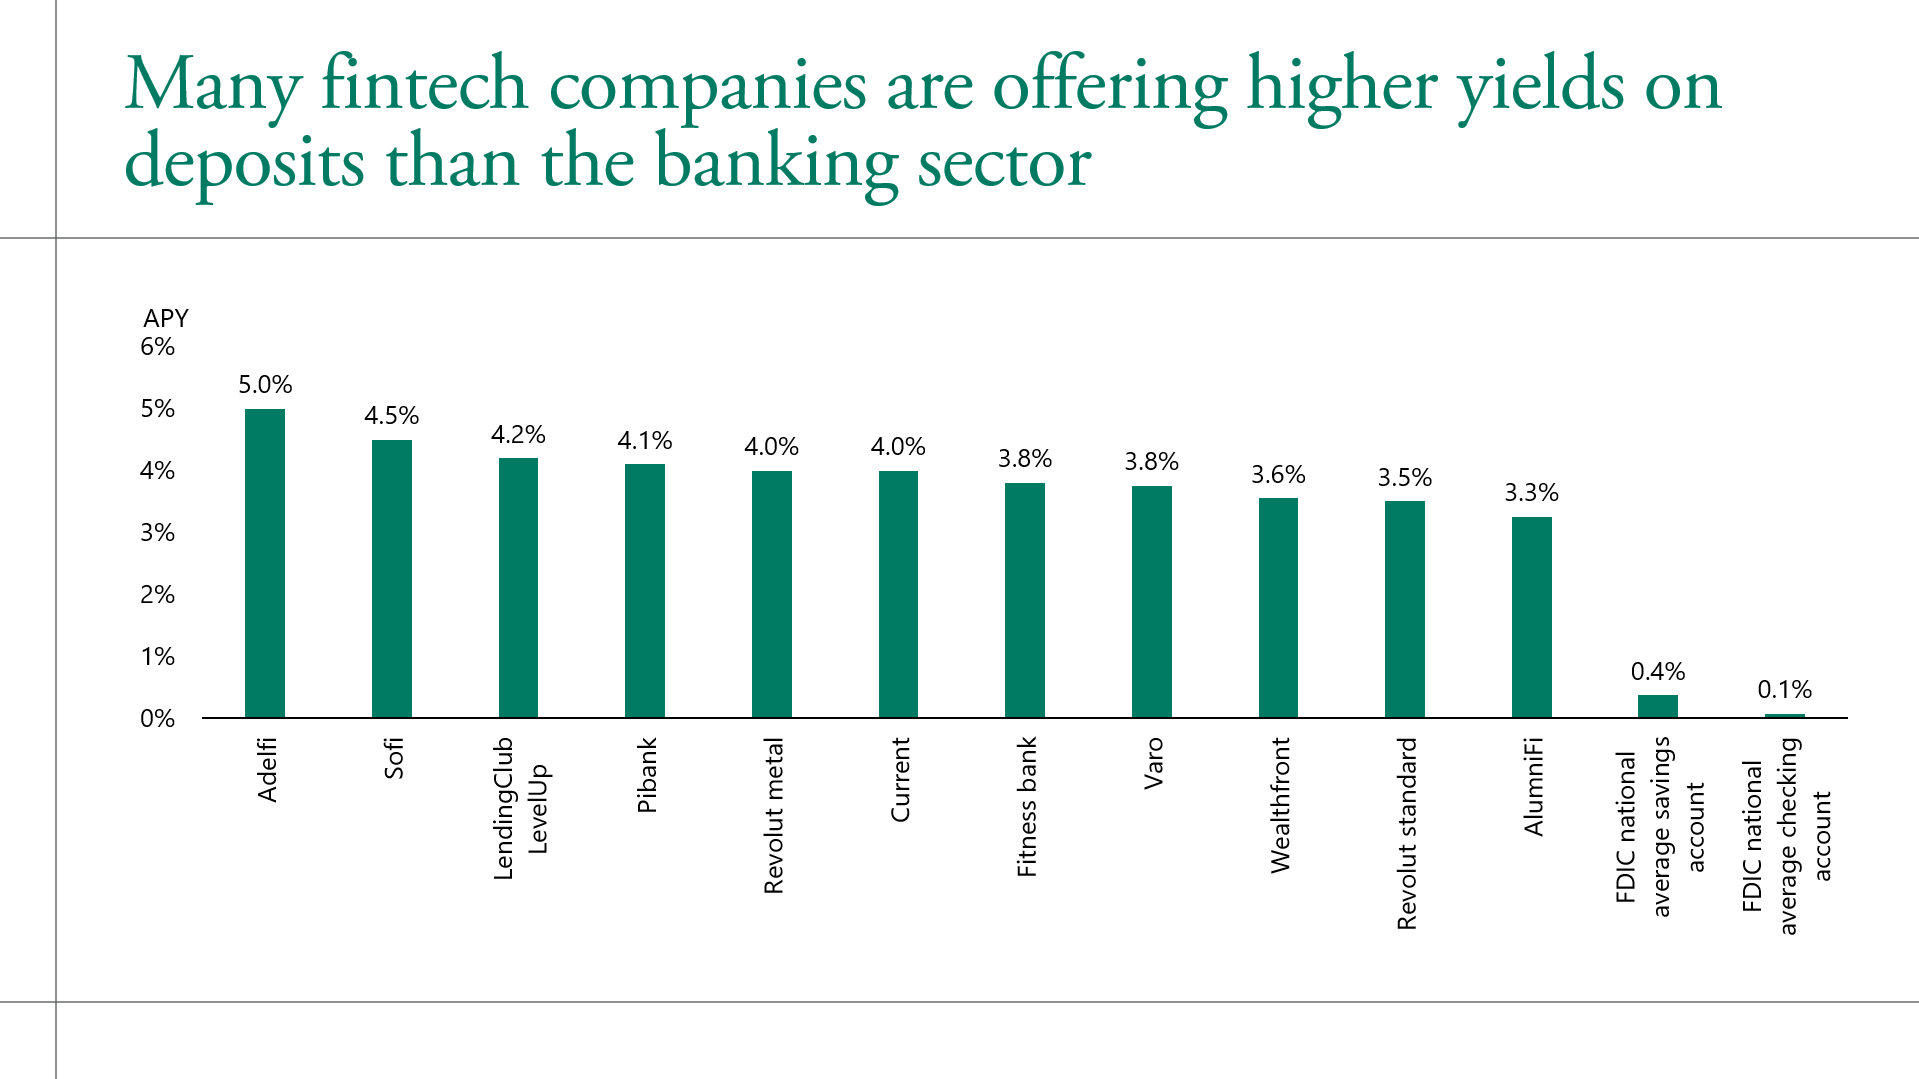
Slok argues that authorized AI agents could automatically move household cash from low-yield checking accounts into higher-yield alternatives. If this became widespread, banks could lose some of the cheap and sticky deposits they use to fund lending.
Why it matters
The scenario illustrates how agents can change an industry by lowering search and switching costs rather than by producing a new good. Faster deposit competition could benefit savers while raising banks’ funding costs and changing how credit is supplied.
What to keep in mind
This is a one-page argument, not an observed bank run or a calibrated forecast. It assumes widespread authorization and trust in financial agents. Deposits may move among banks or fintech partner banks rather than leave the banking system, and banks could respond with higher rates, fees or different funding sources.